

Acting pay rarely arrives on a schedule. A big role can be followed by months of nothing, and the people who last for decades tend to treat that gap as something to plan for.
The approaches below come from actors, working performers and financial advisors who focus on the performing arts. Some are habits learned from family, some are business moves, and some are plain bookkeeping. Where a source is a general financial voice rather than a famous name, that is noted.
Saving First and Paying Taxes Without Complaint
Queen Latifah has credited her money mindset to her mother. She says her money mindset came from her beloved mother. The core advice was simple: put money aside and pay your taxes.
It sounds almost too basic to repeat. Still, those two habits cover the most common reasons performers run into trouble, which are spending everything in a good year and being surprised by a tax bill later.
Spreading Income Across More Than Acting
Latifah has also been open about the value of diversifying income. She has always been honest about her finances, and in a 2020 interview she talked about the importance of diversifying income. Her own path shows what that can look like.
She has been an entrepreneur since her 20s, launching Flavor Unit in 1995 and later expanding into real estate and production deals. The idea is that no single casting decision should decide whether the bills get paid.
Squeezing Value From Every Paycheck
Kyle Timson is a working stage actor, not a household name, but his view comes from years on the road. He is a University of Michigan graduate who has toured as dance captain and male swing on the North American tour of Les Miserables. He says that as a seasoned veteran he sees younger performers repeating his early mistakes.
His mission is to help people maximize every penny they earn, because these jobs are unpredictable. One practical point he raises is that banks with branches on every corner often pay very low savings rates, so where the cash sits matters too.
Building an Off Contract Buffer
A performer writing for Actor Aesthetic describes a specific fund for the gaps between jobs. The fund is called the Off Contract Buffer. It works because money saved while employed covers life when the paychecks stop.
This lets you keep following your spending plan even when no money is coming in, as long as you saved the excess while on contract. The same writer notes that such savings can absorb surprises like car repairs or medical bills, or just a week of rest after a show closes.
Setting Aside Money for Self Employment Taxes
Taxes are where many actors get caught off guard. The Actor Aesthetic writer describes owing the government far more than expected after working a whole year on 1099s.
Advice aimed at working actors echoes this. Casting Networks suggests breaking income up, with about 20 percent going to taxes, and opening a separate checking account just for acting money. Keeping detailed expense records also helps with deductions.
Treating Homes as Long Term Holdings
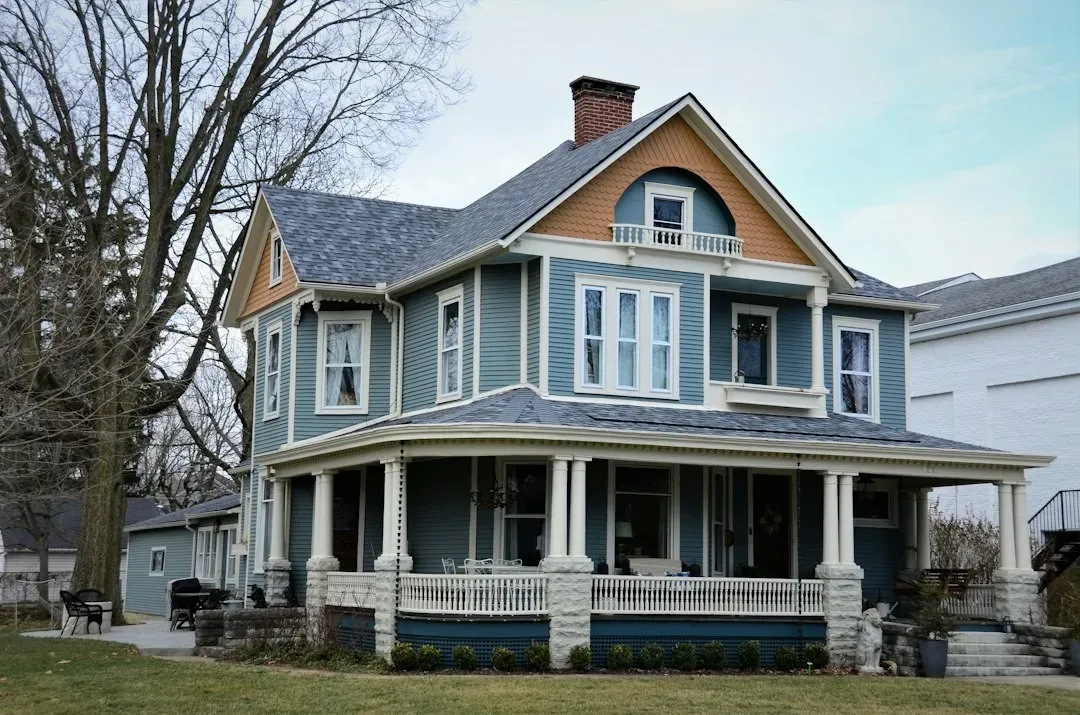
Real estate is a favorite for long running stars, and Ellen DeGeneres is a well known example. She has become one of Hollywood’s most well known house flippers, even if she doesn’t see it that way.
By her own account, she has never bought a place with the aim of selling it. She approaches each purchase as if it were her final home, and the profit comes as a byproduct of that patience.
Owning a Piece of the Business
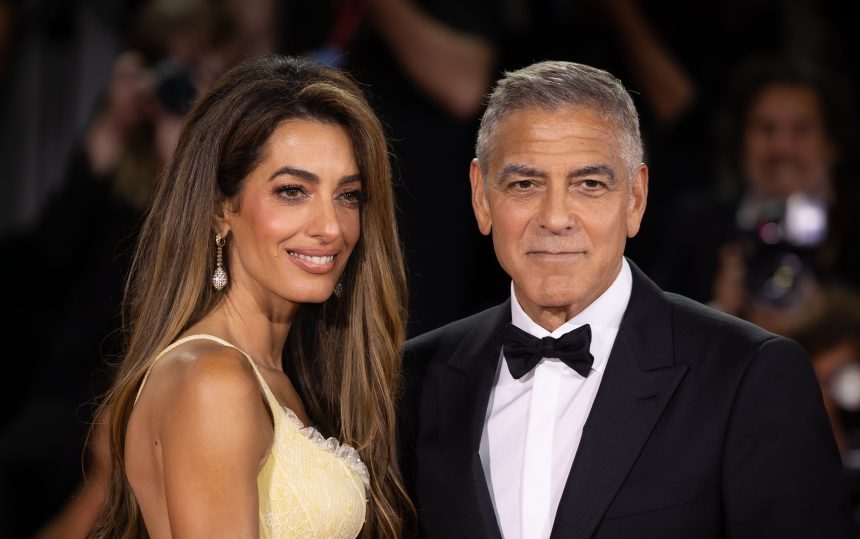
George Clooney’s best known money story involves tequila. He started Casamigos as a tequila meant for his friends, but it blew up and Diageo acquired it for around $1 billion.
The lesson for other actors is about ownership. Earning a fee for a role is one thing, while holding equity in something you built can pay out on a completely different scale.
Planning Retirement Without a Safety Net
Financial advisor Bailie Slevin points out a hard fact for performers. Unless you’re in a union, no one else is putting aside money for your retirement. That makes it the actor’s own job to do the work.
Acting guidance commonly recommends opening a retirement account, such as a 401(k) or an IRA, and contributing regularly. Even small, steady deposits matter, since $5 a week adds up to $240 a year before any growth is counted.